

How Much Cash Do Buyers Need for The MarQ? A Look at Payment Options in August 2026
For a centrally located apartment worth several billion to several tens of billions of Vietnamese dong, the total purchase price is not the only figure buyers need to consider.More practical questions include how much
For a centrally located apartment worth several billion to several tens of billions of Vietnamese dong, the total purchase price is not the only figure buyers need to consider.
More practical questions include how much cash must be prepared at the beginning, when the remaining amount becomes payable and whether future payment obligations will place too much pressure on household cash flow.
The MarQ sales policy updated in August 2026 currently offers several approaches: accelerated payment with an incentive of up to 5%, payment of 50% with immediate handover, an extended payment schedule through 2028, or financing in which buyers prepare 30% of the apartment value and a bank finances up to 70%.
Each option solves a different financial problem. There is no single payment method that is automatically best for every buyer.
What stands out in The MarQ’s current sales policy?
The main difference between the available options is when buyers need to deploy their capital.
Buyers with substantial cash reserves can consider accelerated payment and receive an incentive of up to 5%.
Those wanting to use the apartment sooner may consider paying 50% and taking possession, while buyers wanting to preserve liquidity can explore a payment schedule extending to 2028.
Another option involves financial leverage. Buyers prepare 30% of the apartment value while a bank finances 70%, with an 18-month grace period on both principal and interest.
The information provided also includes title certificates available for transfer, designated car parking spaces and private lifts for three- and four-bedroom units.
These policies are time-sensitive and updated as of August 2026. Actual eligibility and conditions may depend on the individual unit and transaction structure.
Buyers with available cash: is accelerated payment worthwhile?
Accelerated payment is most suitable for buyers who already have most of the required funds and do not need to preserve a large amount of capital for business, investments or other financial plans.
The clearest benefit is the incentive of up to 5%.
On a high-value property, even a few percentage points can represent a substantial amount of money.
For illustration, if a one-bedroom apartment has an asking price of VND 9.8 billion, 5% is equivalent to approximately VND 490 million.
For an apartment priced at VND 27 billion, 5% would equal approximately VND 1.35 billion.
These figures are mathematical illustrations based on the maximum stated incentive. They should not be interpreted as confirmation that every resale property currently listed on Linker qualifies for the full 5% discount.
Buyers should also consider opportunity cost.
If the money used for early payment is currently generating returns through a business or investment portfolio, maintaining liquidity may be more valuable than receiving the discount.
Paying 50% and taking possession: who does this suit?
The 50% payment option addresses a different issue.
It may suit owner-occupiers who want to begin using the apartment relatively quickly without paying the entire purchase price at once.
The MarQ has already been completed, so the situation differs from buying an off-plan property and waiting years for handover.
For someone currently renting, relocating or planning to establish a permanent residence soon, the ability to take possession earlier can have practical value.
For example, on an apartment with an asking price of VND 14 billion, 50% corresponds to approximately VND 7 billion.
For a VND 27 billion apartment, 50% would be around VND 13.5 billion.
These examples are intended only to illustrate the scale of capital involved.
The remaining 50% still needs to be planned from the beginning. Being able to take possession does not remove future payment obligations.
How does an extended payment schedule through 2028 help cash flow?
Not every buyer chooses a longer payment schedule because they lack money.
For many affluent buyers, preserving liquidity can be more important than paying the entire property value immediately.
An extended schedule through 2028 allows financial obligations to be spread over a longer period. This can give buyers more time to accumulate income, restructure other assets or keep capital available for business activities.
Someone who can technically afford The MarQ outright may still prefer a longer schedule if that capital is more useful elsewhere.
The trade-off is that the buyer may not maximize incentives available under accelerated payment.
Another important point is that “payment through 2028” does not necessarily mean equal monthly installments.
Buyers should examine the actual payment milestones and compare each installment against expected cash flow.
Preparing 30% and borrowing 70%: what needs to be calculated?
This option reduces initial capital requirements significantly, but it also creates the largest future financial obligation.
Under the policy provided, buyers prepare 30% of the apartment value while a bank finances 70%. The loan includes an 18-month grace period on principal and interest.
Using current asking prices on Linker as simple illustrations, a VND 9.8 billion apartment would require approximately VND 2.94 billion for the 30% portion, while 70% corresponds to about VND 6.86 billion.
For a VND 14 billion apartment, 30% equals approximately VND 4.2 billion and 70% equals around VND 9.8 billion.
At VND 27 billion, the respective amounts would be about VND 8.1 billion and VND 18.9 billion.
For a VND 33 billion apartment, 30% corresponds to roughly VND 9.9 billion, while 70% would be around VND 23.1 billion.
These calculations are only intended to illustrate the scale of financing. They do not mean that every resale apartment listed on Linker qualifies for this loan program.
The period buyers should examine most carefully is what happens after the 18-month grace period.
Once normal loan obligations begin, the monthly burden will depend on the actual outstanding principal, interest rate and repayment structure.
Therefore, having enough money for the initial 30% does not automatically mean the property is affordable.
Buyers should also consider stable after-tax income, existing debts, household expenses and an emergency reserve.
Accelerated payment, extended payment or bank financing?
Buyers with substantial cash and sufficient reserves after the purchase may prefer accelerated payment to reduce their overall cost.
Those with strong financial capacity but who want to preserve capital for business or investments may be better suited to the extended schedule through 2028.
Bank financing may suit buyers who want to minimize the initial cash requirement but have sufficiently stable income to handle future repayments.
Instead of asking which policy is “best”, buyers should determine what they are trying to optimize: total purchase cost, liquidity or initial capital.
How do title certificates, parking and private lifts affect the decision?
Payment terms are only one part of the purchase decision.
A title certificate available for transfer allows buyers to check the legal status of an individual property before completing the transaction. For a completed development, this should be reviewed on a unit-by-unit basis.
A designated car parking space addresses a very practical issue for households that own vehicles, particularly in a dense central district.
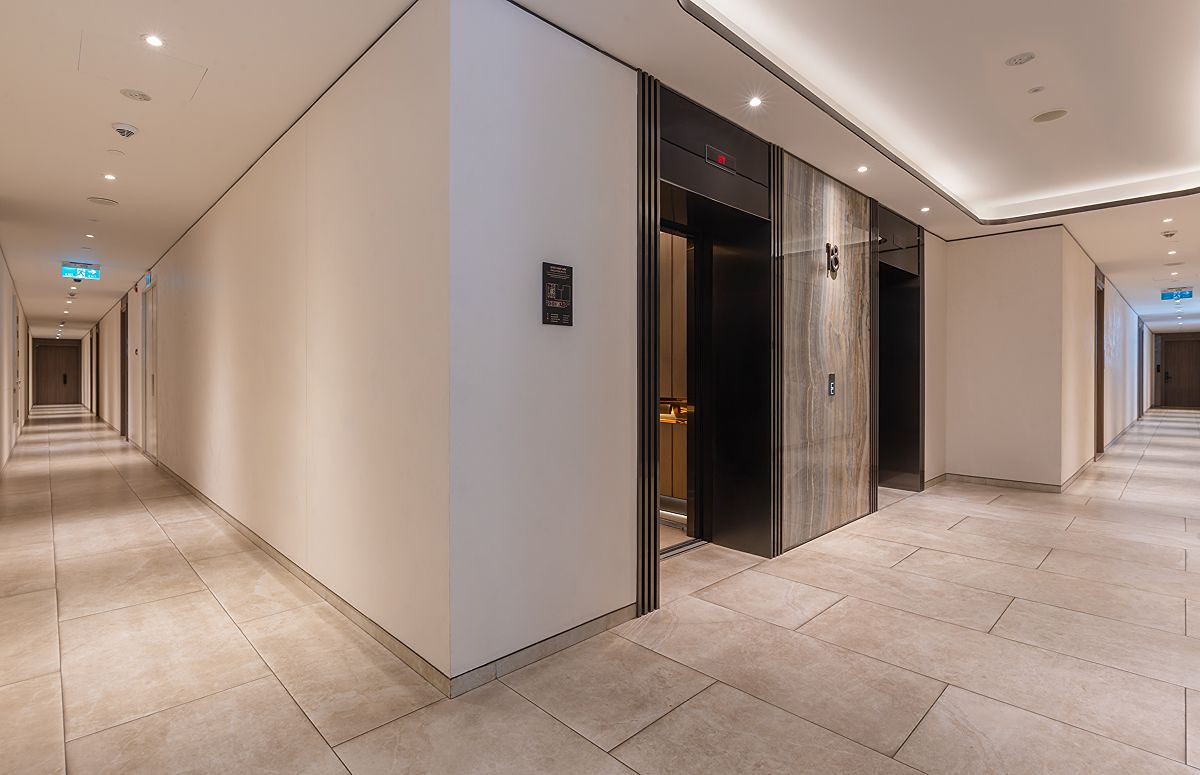
For three- and four-bedroom units, private lifts can provide additional privacy when entering or leaving the apartment.
Their importance varies according to the buyer’s household structure and lifestyle, so they should be considered as functional features rather than purely promotional privileges.
What type of The MarQ apartment fits different budgets?
A one-bedroom apartment offers a lower total entry price than larger units and is generally more relevant to single occupants, couples and professionals.
Two-bedroom apartments provide greater flexibility for small families and buyers who need an additional bedroom or home office.
Three-bedroom apartments target households requiring more permanent family space. At this price level, differences in floor, view, interior condition and legal status become increasingly important.
Four-bedroom units are intended for larger families or buyers who want significantly more space while remaining in central Ho Chi Minh City.
Because total prices are substantially higher, financing decisions and the use of leverage require more careful planning.
The MarQ properties currently attracting attention
Linker data for August 2026 includes a one-bedroom apartment of approximately 51 sqm with an asking price of VND 9.8 billion.
If 30% is used purely as a budgeting illustration, that corresponds to approximately VND 2.94 billion in initial capital.
Two-bedroom apartments of around 72–77 sqm are listed across several price levels. Using an asking price of VND 14 billion as an example, 30% would correspond to approximately VND 4.2 billion.
Three-bedroom apartments of around 107–110 sqm are currently listed from above VND 20 billion to approximately VND 27 billion. At VND 27 billion, 30% would be around VND 8.1 billion.
Four-bedroom apartments of approximately 144–146 sqm begin from around VND 33 billion in the current listing data. At that level, 30% would correspond to approximately VND 9.9 billion.
These figures are not payment conditions attached to individual Linker listings. They simply help readers understand the scale of capital involved.
Buyers can review the wider range of one-, two-, three- and four-bedroom apartments through the overall The MarQ sales page on Linker.
Ultimately, the answer to “How much money do I need to buy at The MarQ?” depends heavily on how the buyer structures the purchase.
Some buyers may deploy more capital upfront to reduce total cost, while others may preserve liquidity by extending payment or using bank leverage.
A more useful starting point is to define three figures: available cash today, sustainable monthly housing expenditure and the amount of emergency capital that should remain untouched.
Once those numbers are clear, choosing between accelerated payment, payment through 2028 or 70% bank financing becomes far more practical.
The sales policies discussed in this article are updated as of August 2026. Actual payment schedules, financing conditions and associated benefits may vary depending on the unit and transaction at the time of purchase.